September 2026 | 922 words | 4-minute read


A Rs 12 lakh home loan in a Tier-3 town. A Rs 1cr working capital loan for a growing engineering firm. A personal loan funding a life milestone. Different needs, but all illustrate a broader trend: aspirations beyond India’s largest cities increasingly depend on access to organised credit.
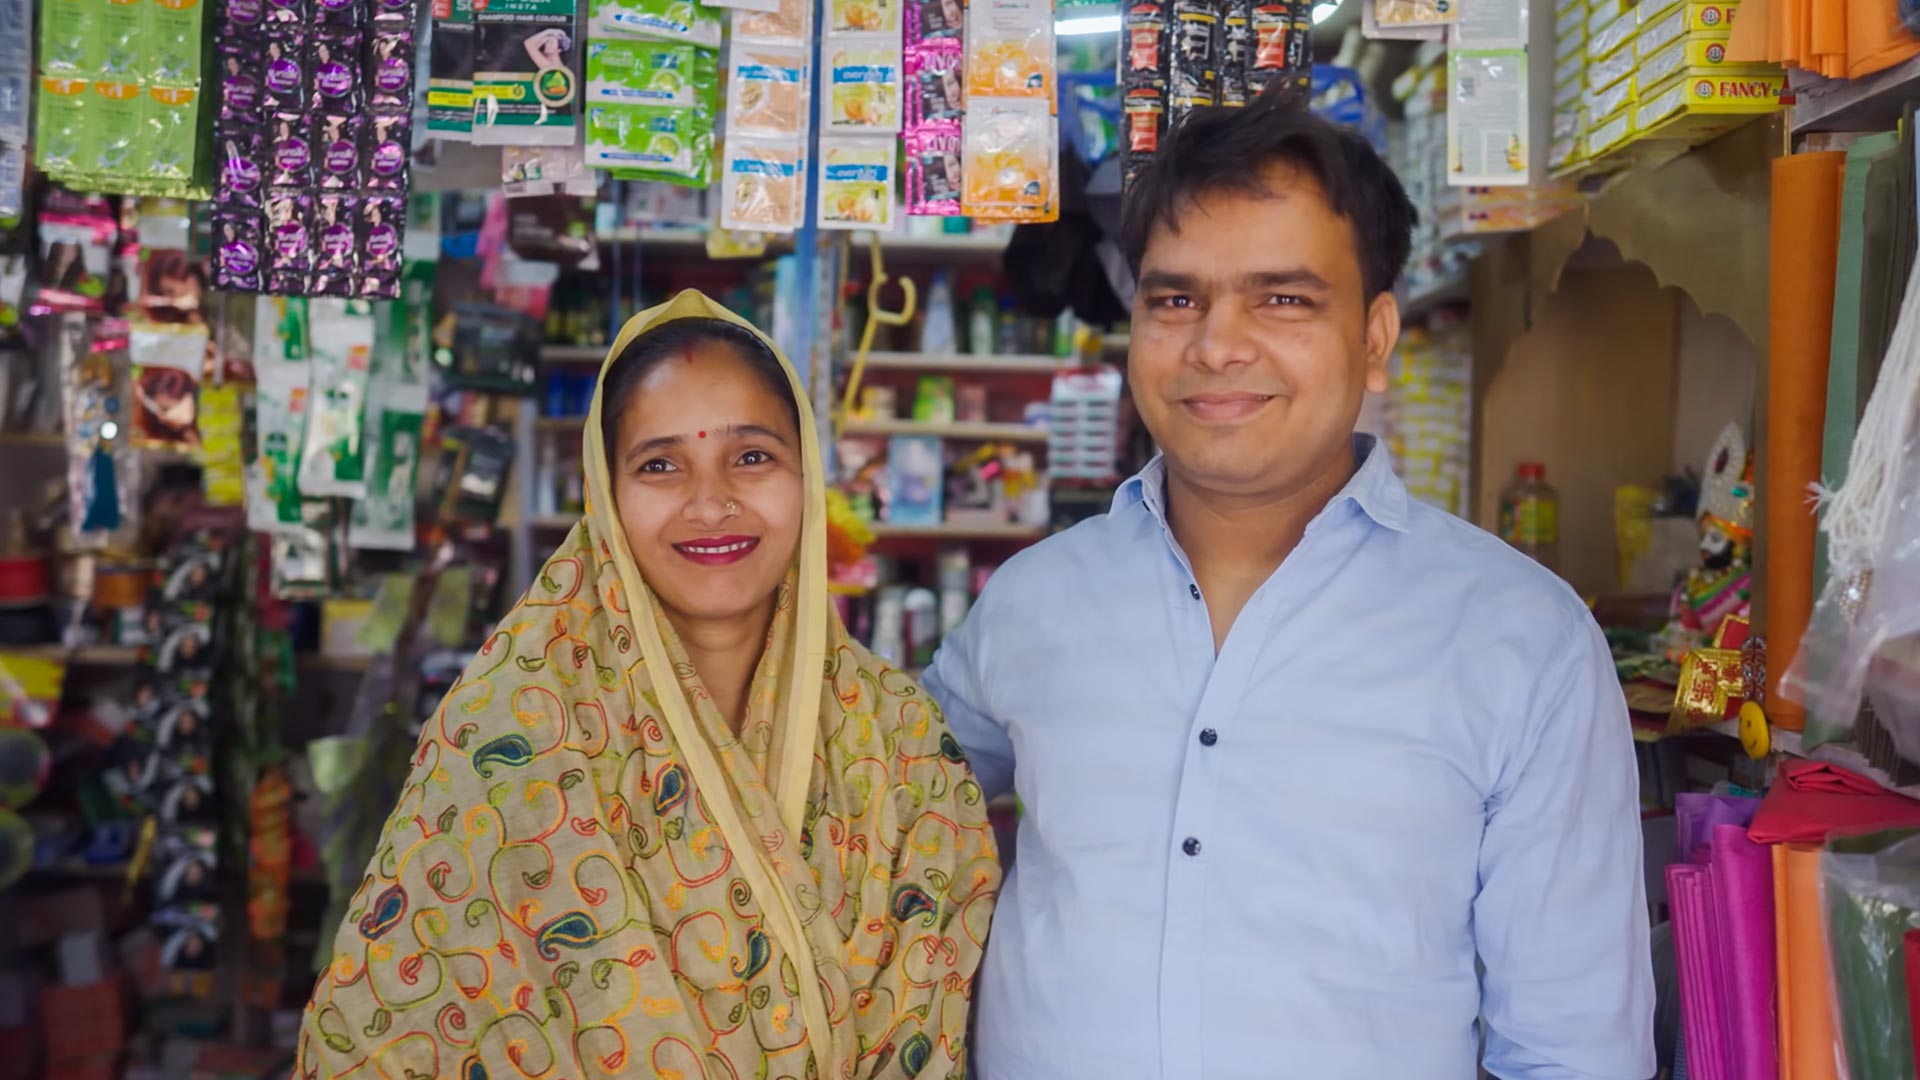
Tata Capital’s experience across retail, housing, and small and medium-sized enterprise (SME) finance, captures this shift. Customers in smaller towns aren’t just seeking loans; they are seeking participation in India’s formal economy. From first-generation entrepreneurs and self-employed professionals to families building homes, they represent a new wave of borrowers whose ambitions extend well beyond subsistence.
A home run
Affordable housing has emerged as a major growth driver for Tata Capital Housing Finance. “Since expanding aggressively into Tier-3 and Tier-4 markets following the pandemic, Tata Capital Housing Finance has grown from about 100 branches to more than 350, with virtually all recent expansion taking place in smaller cities and towns,” says Sarosh Amaria, Managing Director, Tata Capital Housing Finance. Today, affordable housing accounts for ~Rs 16,000cr of its Rs 68,000cr retail loan book and is expected to grow at over 30% annually.
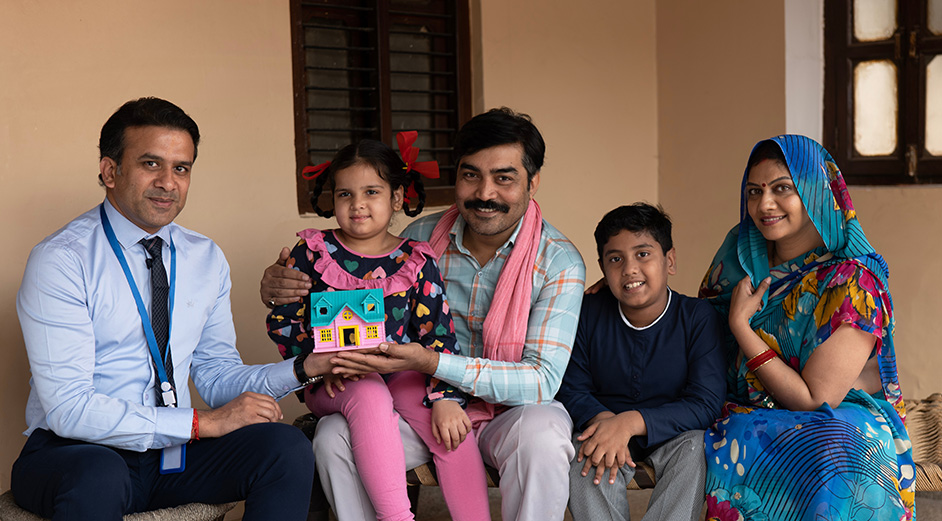
The opportunity lies in markets where aspirations are rising faster than access to formal credit. As self-construction, plot purchases and first-time home ownership increase, many borrowers still lack conventional income documents and often depend on informal lenders charging significantly higher interest rates.
Serving these customers required more than new products. Tata Capital Housing Finance has broadened its approach to credit assessment, looking beyond salary slips and formal income documentation to evaluate cash flows, business activity, digital payment records and other locally relevant indicators to gauge repayment capacity. The aim is to reflect the realities of borrowers traditionally underserved by the formal financial system.
Growth at a glance
- ~750 branches (of 1,477) in Tier-2+ cities
- 90% of branches in Tier-2+ cities
- 80%+ of these are in Tier-3 and rural areas
- 40% of retail finance business comes from Tier-2+
- 300 affordable housing finance branches in Tier-3+
- ₹16,000cr affordable housing portfolio
- ₹15L- ₹18L average affordable housing loan size
- ₹25L-₹5cr average SME loan range
- ₹50,000+ microfinance loan size
*All data as of FY26
Small businesses, big dreams
The changing face of non-metro India is also visible in the ambitions of local entrepreneurs. Across manufacturing and trading hubs, SMEs are investing in equipment, expanding capacity and entering formal supply chains. Much of this is being fuelled by local enterprise rather than large corporate investment alone.
According to Narendra Kamath, Chief Operating Officer, SME Finance, Tata Capital, this is one of the defining shifts underway in the economy. “The traditional distinction between metro and non-metro businesses is becoming less relevant as industrial ecosystems mature across a wider geography,” he says. “Manufacturing clusters, ancillary industries and local entrepreneurs are creating demand for formal finance in markets that, until recently, lay outside the mainstream lending landscape.”
Recognising that each industrial cluster has distinct financing needs, Tata Capital has tailored its SME strategy to local economies. “Industrial clusters often develop around a particular sector — engineering, textiles, auto components, food processing or pharmaceuticals — each with its own business cycles, financing requirements and growth trajectory,” says Mr Kamath. As these ecosystems expand, so does the need for formal credit.
That same trend is evident in retail lending. “Whether purchasing a vehicle, financing education, improving a home or meeting personal financial milestones, customers are demonstrating greater confidence in engaging with formal financial institutions,” says Vivek Chopra, Chief Operating Officer – Retail Business, Tata Capital. In the last five years, Tata Capital’s retail business has significantly expanded its footprint in these markets. Today, ~90% of its branches are in Tier-2 and smaller centres, and ~80% of those are in Tier-3 and rural areas.
How emerging India borrows
- Homes: First-time ownership and self-construction
- Businesses: Machinery, working capital and capacity expansion
- Consumers: Education, healthcare, vehicles, and home improvement
- Digital confidence: Comfortable with digital processes backed by local trust
- Formalisation: Organised credit is replacing informal borrowing, aided by GST, UPI and digital records
Digitisation and personalisation
Technology has accelerated growth. “Contrary to conventional assumptions, digital adoption in many Tier-3 and Tier-4 markets has been remarkably high, with e-KYC, digital documentation and e-signatures now commonplace among home loan customers,” says Mr Amaria. Tata Capital has also invested heavily in its own technology stack.
Yet, Tata Capital’s experience across housing, retail and SME finance suggests that technology helps, but trust remains central. Customers often begin their journey online but continue to rely on local branches and relationship managers when making major financial decisions, particularly first-time borrowers. As Mr Chopra notes, “One-third of our two-wheeler loans are to new credit customers,” highlighting the importance of awareness initiatives like Sawaal Karo, Phir Loan Lo.
In SME lending, technology enables deeper reach into value chains, but it cannot replace personal engagement. “An SME may apply for a loan for a machine, but that opens up an opportunity for working capital funding to buy raw material and perhaps expands opportunities beyond these requirements,” says Mr Kamath. “These opportunities emerge when we engage with the consumer.”
The story of non-metro India is one of increasing economic participation. Formal finance is helping families buy homes, entrepreneurs expand businesses, and first-time borrowers establish financial identities — turning aspiration into opportunity, one customer at a time.
Together, these business stories reveal that smaller cities are no longer catching up; they are charting their own growth story. By aligning with these strategies, Tata companies are positioning themselves alongside a new generation of customers whose aspirations are reshaping India and powering its next wave of growth.
— Anuradha Anupkumar